In short: Environmental topics get most attention, but the social and governance parts of ESG carry their own legal duties and risks. UK employers with 250 or more employees must publish gender pay gap figures every year; organisations with turnover of £36 million or more that supply goods or services in the UK must publish a modern slavery statement; and the EU CSDDD now applies only to the largest groups, from 2029. Investors also look closely at board composition, executive pay linked to ESG targets and anti-corruption controls. TaxDigit's sustainability and payroll specialists calculate, review and draft these disclosures.
The social and governance disclosures that matter most
Social metrics cover how a business treats its workforce, the people in its supply chain, its customers and the communities around it: diversity and inclusion, pay equity, training, health and safety, and human rights. Human rights in the supply chain are usually the hardest to control, so effort should go first to the highest-risk countries, sectors and suppliers.
Governance metrics show how the business is run: board skills, independence and diversity, committee roles, executive remuneration and the share of incentives tied to ESG targets, the CEO pay ratio, anti-corruption policies and training, and tax transparency. These are among the first things investors and rating agencies check.
- Employers with 250 or more staffAnnual gender pay gap calculations and narrative.
- Organisations with £36m or more turnoverModern slavery statements and supply chain due diligence.
- Large and listed groupsBoard, remuneration and governance disclosures.
- Very large groups with EU turnoverChecking the narrowed CSDDD scope.
Led by Dr Attieh Moezoddin, Head of Sustainability & ESG Advisory (PhD, Built Environment)Reviewed by Amir Rafiei, ACCA Certificate in Sustainability for FinanceLast reviewed
What we do
Gender pay gap reporting
Snapshot-date payroll data, mean and median hourly pay and bonus gaps, bonus proportions and pay quartiles, with an explanatory narrative.
Modern slavery statements
Risk mapping by country, sector and supplier, policies, due diligence steps and KPIs, drafted for board approval and the government registry.
Supply chain due diligence
Supplier codes, audit frameworks and data exchange, following the step-by-step collaboration approach from commitment to co-engineering.
Governance disclosures
Board composition, skills matrix, independence, committee roles and diversity data for the annual report and ESG ratings.
ESG-linked pay
Designing and disclosing ESG measures in bonus and long-term incentive plans, including the CEO pay ratio where required.
EU due diligence scope check
Whether the CSDDD applies to your group after the Omnibus changes and, if so, what it requires and when.
Social and governance reporting duties
| Duty | Who | What |
|---|---|---|
| Gender pay gap reporting | GB employers with 250 or more employees | Mean and median hourly pay gap, bonus gaps, proportion receiving bonuses and pay quartiles, published annually |
| Modern slavery statement (s54 Modern Slavery Act 2015) | Commercial organisations supplying goods or services in the UK with turnover of £36m or more | Annual statement of steps taken to prevent slavery and human trafficking in the business and supply chains |
| Payment practices reporting | Large UK companies and LLPs | Half-yearly reports on payment terms and performance |
| Section 172 statement | Large UK companies | How directors have had regard to employees, suppliers, customers, community and environment |
| EU CSDDD (after Omnibus I) | EU companies with more than 5,000 employees and €1.5bn turnover; non-EU companies with more than €1.5bn EU turnover | Human rights and environmental due diligence, from 2029 |
How we help
Payroll, HR, procurement and board data collected and checked.
Pay gap figures, risk scores and governance metrics.
Statements and narrative for board approval.
Government portals, website and annual report.
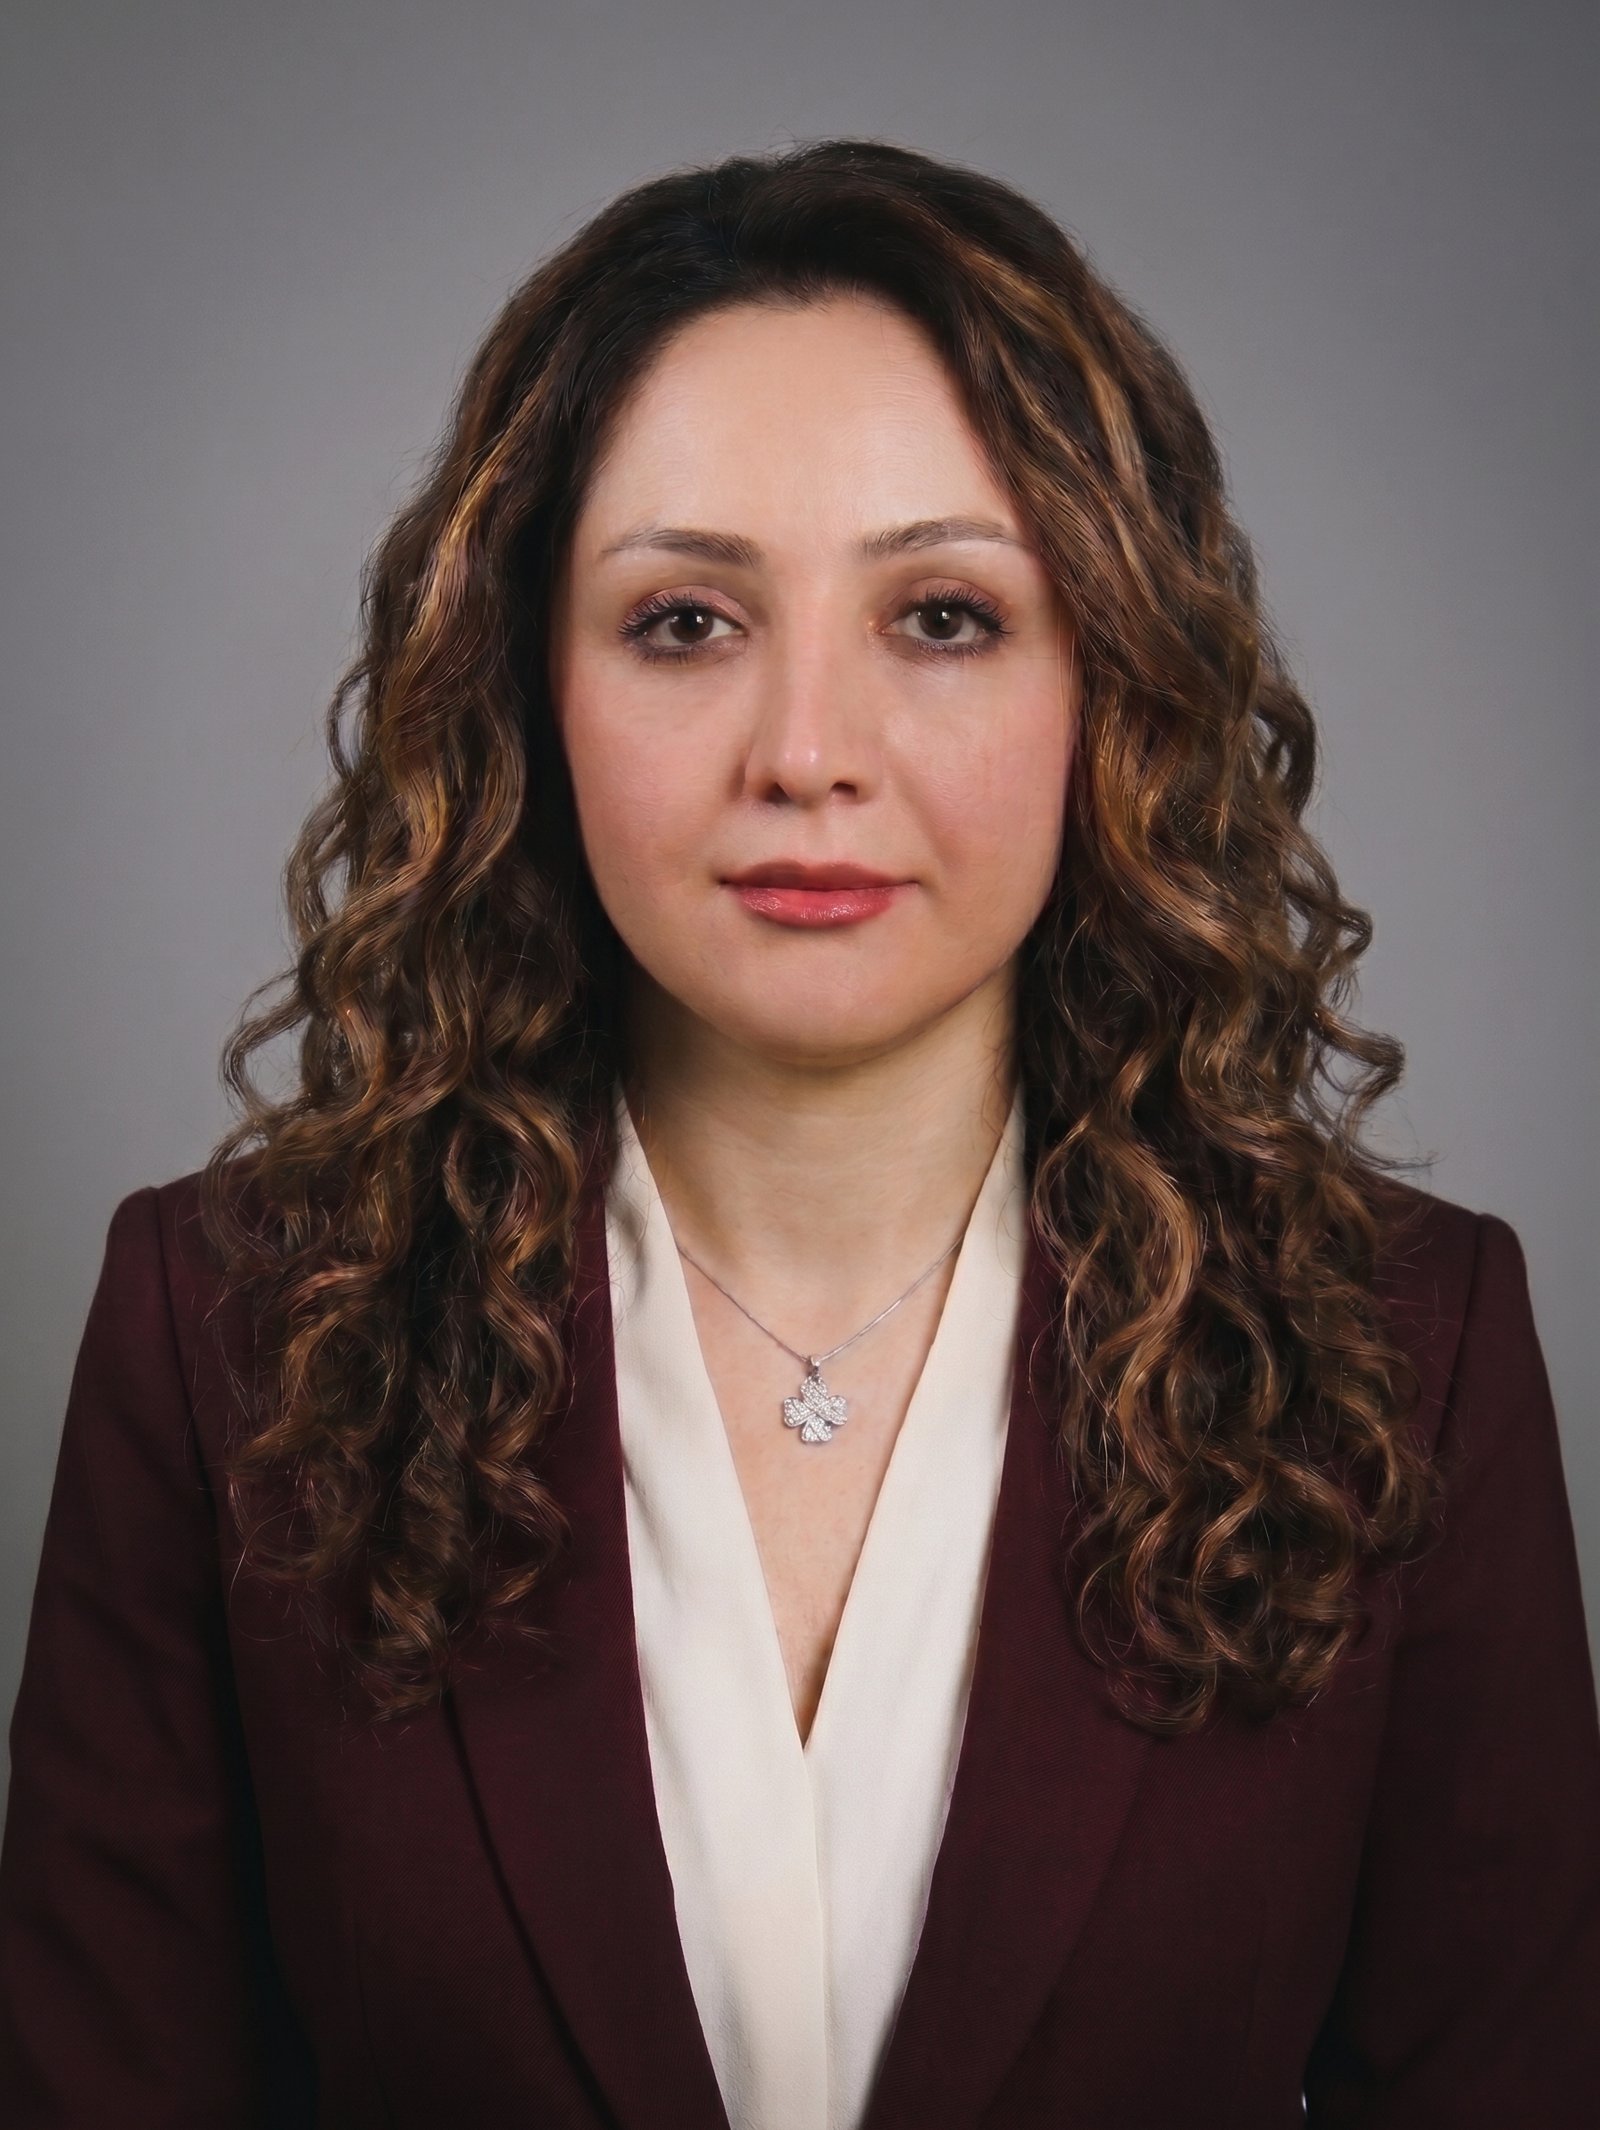
A dedicated sustainability and ESG team
TaxDigit has a dedicated sustainability and ESG team, led by Dr Attieh Moezoddin, Head of Sustainability & ESG Advisory. Attieh holds a PhD in the Built Environment from the University of Salford and is a sustainable development researcher whose doctoral work built a framework for sustainable urban development using expert panels and multi-criteria analysis (fuzzy Delphi, fuzzy AHP and fuzzy TOPSIS) across social, environmental, economic and cultural pillars.
Finance, reporting and tax quality is reviewed by Amir Rafiei, Senior Manager for Global Tax Strategy, Transfer Pricing and Sustainability, who holds the  ACCA Certificate in Sustainability for Finance. The team works side by side with our accounts, tax, payroll and international specialists, so your sustainability disclosures, financial statements and tax returns rest on one set of facts. Statutory audit is carried out separately by our alliance firm Jelveh Audit & Assurance.
- PhD, Built Environment
- Sustainable development research
- Materiality and expert panels
- SDGs and impact
- Climate risk and reporting
- ESG metrics and analytics
- IFRS S1, S2 and UK SRS
- CSRD and ESRS
- CBAM and green taxes
All sustainability and ESG services
See the full overview on our sustainability and ESG services page, or go straight to a related service. Large groups may also need our large and multinational group tax support.
Official sources
Rules, thresholds and dates on this page were checked against these sources on 14 November 2026. We re-check them whenever they change.
Frequently asked questions
Who must report their gender pay gap?
Employers in Great Britain with 250 or more employees on the snapshot date. Private and voluntary sector employers use a 5 April snapshot date.
What is the difference between the gender pay gap and equal pay?
The pay gap compares average earnings of men and women across the organisation regardless of role. Equal pay is the legal right to equal pay for equal work.
Who must publish a modern slavery statement?
Commercial organisations carrying on business in the UK that supply goods or services and have a total turnover of £36 million or more.
Why is supply chain human rights so hard to manage?
Because it depends on suppliers you do not control, often in several tiers and countries. Focus on the highest-risk areas first and build collaboration with key suppliers.
Does the CSDDD apply to UK companies?
Only to non-EU companies with more than €1.5bn of EU turnover after the Omnibus changes, from 2029. Most UK groups are outside it, but their EU customers may still ask for due diligence information.
Is executive pay a social or governance metric?
Governance. Board composition, executive remuneration and anti-corruption are governance topics.
Can you calculate our gender pay gap from our payroll?
Yes. Our payroll team works with your data on the snapshot date and we prepare the figures and narrative for publication.
Should ESG targets be part of bonuses?
Many listed companies now include ESG measures in incentives. They work best when they are material, measurable and verified.