In short: The EU's Omnibus I Directive, in force since 18 March 2026, cut the CSRD back sharply. EU companies and groups now report only if they have more than 1,000 employees and more than €450m of net turnover, starting with financial years from 2027. Non-EU groups, including UK groups, report only if they have more than €450m of EU turnover and an EU subsidiary or branch with more than €200m, from financial year 2028 with reports in 2029. Smaller companies are protected from excessive data requests through the voluntary VSME standard. TaxDigit's sustainability team tells you which entities are in scope, runs the double materiality assessment and prepares ESRS or VSME reporting.
Who the CSRD now catches
The CSRD still uses double materiality: you report on sustainability matters that affect the company (financial materiality, outside-in) and on the company's impacts on people and the environment (impact materiality, inside-out). Reports follow the European Sustainability Reporting Standards (ESRS), which are being simplified, and include EU Taxonomy alignment. Companies in scope must still disclose their climate transition plan where they have one.
For UK businesses the question is usually one of three: is our EU subsidiary in scope on its own or as part of an EU sub-group; does our worldwide group pass the non-EU test; or are we simply being asked for data by an EU customer. Each has a different answer and a different workload, so scoping comes first.
- UK groups with EU subsidiariesTesting EU sub-groups against the 1,000 employee and €450m turnover thresholds.
- Non-EU parent groupsApplying the €450m EU turnover and €200m subsidiary or branch tests from FY2028.
- EU subsidiaries that fell out of scopeDeciding whether to keep reporting voluntarily for investors and lenders.
- Suppliers to EU groupsAnswering data requests within the limits of the VSME standard.
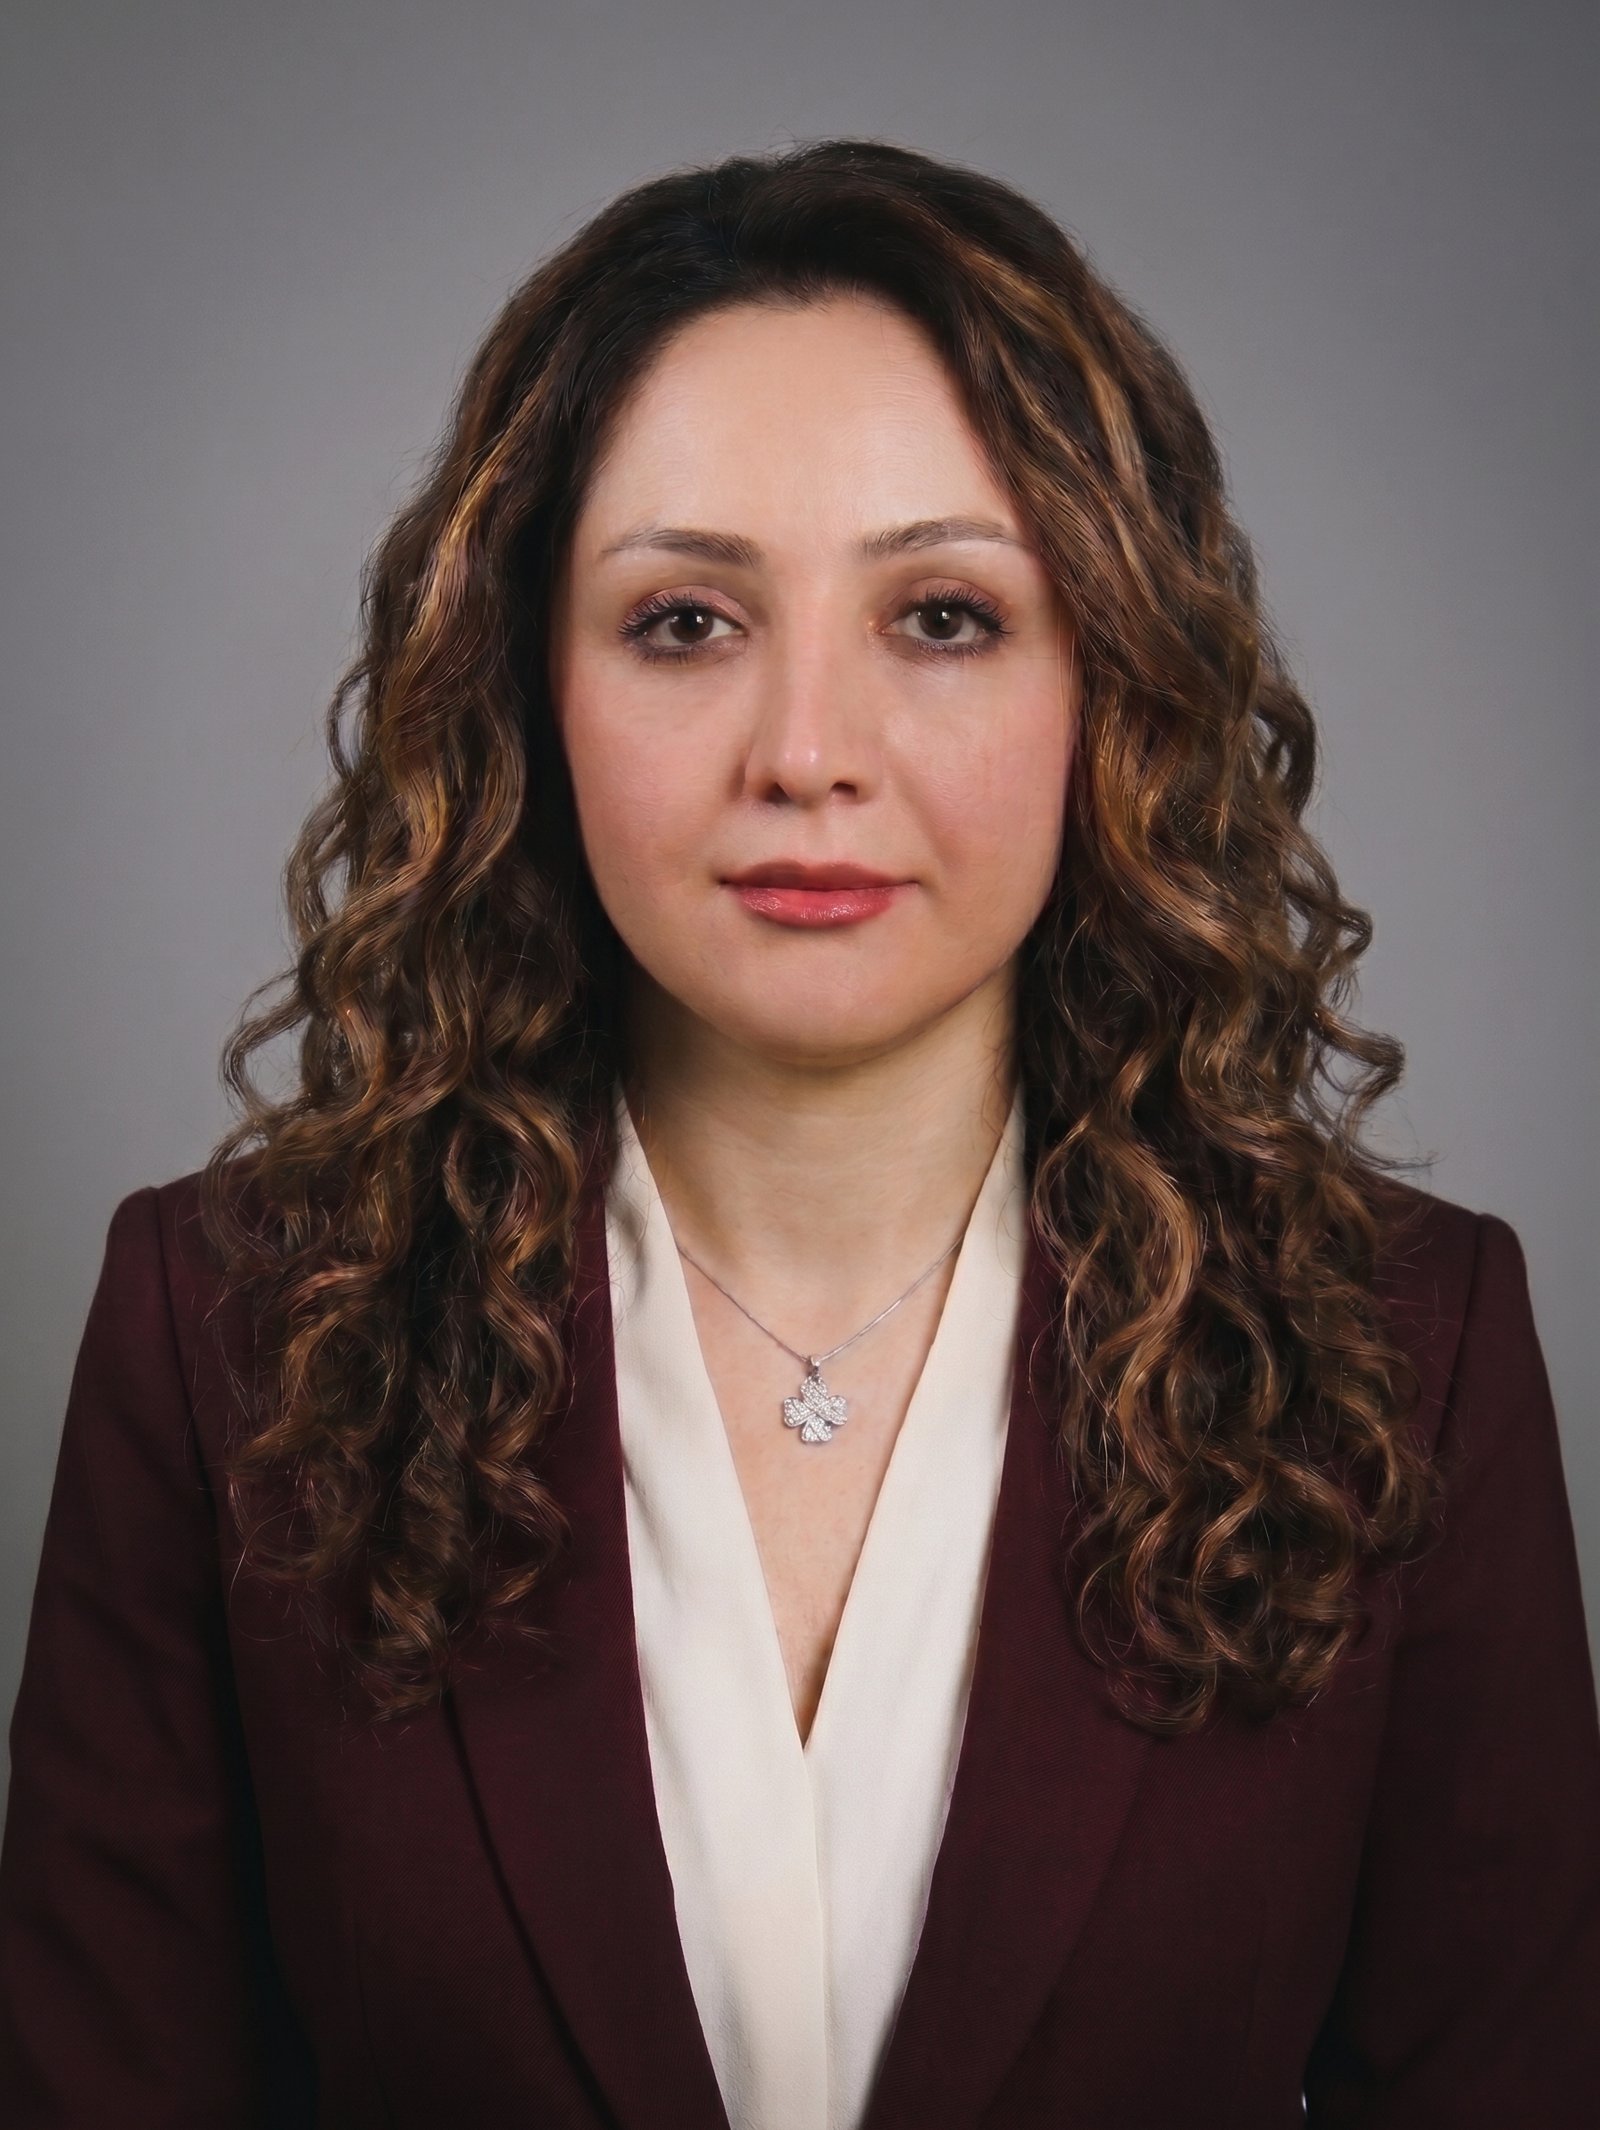
Led by Dr Attieh Moezoddin, Head of Sustainability & ESG Advisory (PhD, Built Environment)Reviewed by Amir Rafiei, ACCA Certificate in Sustainability for FinanceLast reviewed
What we do
Entity-by-entity scope test
We map your group, apply the EU and non-EU thresholds and the exemptions, and give you a clear list of who reports, from when, and on what basis.
DMA that stands up to review
We identify impacts, risks and opportunities across your value chain, score them and document the process so your assurance provider can follow it.
Sustainability statement
We prepare the ESRS sustainability statement or the non-EU group report, with data points, narrative and EU Taxonomy disclosures.
One dataset for ISSB and ESRS
Where you also report under UK SRS or IFRS S1 and S2, we build one dataset and map it to both. See UK SRS and ISSB reporting.
Supplier data packs
For companies with fewer than 1,000 employees, we prepare a VSME-based data pack so you can answer EU customers without building a full CSRD report.
CSDDD check
We confirm whether the much narrower CSDDD applies to your group and what it would require. See social, governance and human rights.
CSRD scope after Omnibus I
| Group type | Test | Reporting starts |
|---|---|---|
| EU companies and groups | More than 1,000 employees and more than €450m net turnover | Financial years beginning on or after 1 January 2027 (reports in 2028) |
| Non-EU parent groups (including UK) | More than €450m net turnover in the EU, plus an EU subsidiary or branch with more than €200m | Financial year 2028 (reports in 2029) |
| Wave 1 companies now below the thresholds | Member States may exempt them | Financial years 2025 and 2026 |
| Smaller value-chain partners | Fewer than 1,000 employees: requests limited to the VSME standard | Applies to requests from in-scope reporters |
| Financial holding companies | Exempt from sustainability reporting | Under the Omnibus text |
Member State transposition can differ in detail. We check the law of the Member State where your EU entity is based.
How a CSRD engagement runs
Group map and scope test for every EU entity and the group as a whole.
Impacts, risks and opportunities assessed and documented.
Data collection, Taxonomy alignment and the sustainability statement.
Evidence, controls and review before the limited assurance engagement.
A dedicated sustainability and ESG team
TaxDigit has a dedicated sustainability and ESG team, led by Dr Attieh Moezoddin, Head of Sustainability & ESG Advisory. Attieh holds a PhD in the Built Environment from the University of Salford and is a sustainable development researcher whose doctoral work built a framework for sustainable urban development using expert panels and multi-criteria analysis (fuzzy Delphi, fuzzy AHP and fuzzy TOPSIS) across social, environmental, economic and cultural pillars.
Finance, reporting and tax quality is reviewed by Amir Rafiei, Senior Manager for Global Tax Strategy, Transfer Pricing and Sustainability, who holds the  ACCA Certificate in Sustainability for Finance. The team works side by side with our accounts, tax, payroll and international specialists, so your sustainability disclosures, financial statements and tax returns rest on one set of facts. Statutory audit is carried out separately by our alliance firm Jelveh Audit & Assurance.
- PhD, Built Environment
- Sustainable development research
- Materiality and expert panels
- SDGs and impact
- Climate risk and reporting
- ESG metrics and analytics
- IFRS S1, S2 and UK SRS
- CSRD and ESRS
- CBAM and green taxes
All sustainability and ESG services
See the full overview on our sustainability and ESG services page, or go straight to a related service. Large groups may also need our large and multinational group tax support.
Official sources
Rules, thresholds and dates on this page were checked against these sources on 14 November 2026. We re-check them whenever they change.
Frequently asked questions
Does CSRD apply to UK companies?
A UK company is not caught directly, but its EU subsidiaries may be, and the UK parent group may have to report if it has more than €450m of EU turnover and an EU subsidiary or branch with more than €200m, from financial year 2028.
What are the new CSRD thresholds?
For EU companies and groups, more than 1,000 employees and more than €450m net turnover. For non-EU groups, more than €450m of EU turnover plus an EU subsidiary or branch above €200m.
When did the Omnibus changes take effect?
The Omnibus I Directive was adopted on 24 February 2026, published in the Official Journal on 26 February 2026 and entered into force on 18 March 2026. Member States then transpose it.
What is double materiality?
Reporting both on how sustainability matters affect the company's development, performance and position (financial materiality) and on the company's impacts on people and the environment (impact materiality).
Our customer in the EU wants ESG data. Do we have to produce a CSRD report?
No. If you have fewer than 1,000 employees you are a protected value-chain partner, and in-scope reporters should not ask for more than the voluntary VSME standard covers. We prepare a VSME-based pack for you.
Is EU Taxonomy reporting still required?
For companies within the new CSRD scope, yes, using the revised Taxonomy rules. Companies outside the CSRD scope fall outside the Taxonomy reporting requirement.
Does the CSRD report need assurance?
Yes, limited assurance is required for in-scope reporters. We prepare your data and documentation for the assurance provider. See ESG data and assurance readiness.
Can one dataset serve CSRD and UK SRS?
Largely, yes. The ISSB and EFRAG have published interoperability material, and we build one dataset with mapping to both, while recognising that ESRS covers impact materiality and more topics.
Do you advise on the law of each EU Member State?
We work from the Directive and each Member State's transposition and, where local legal or filing advice is needed, coordinate with a local adviser you appoint.