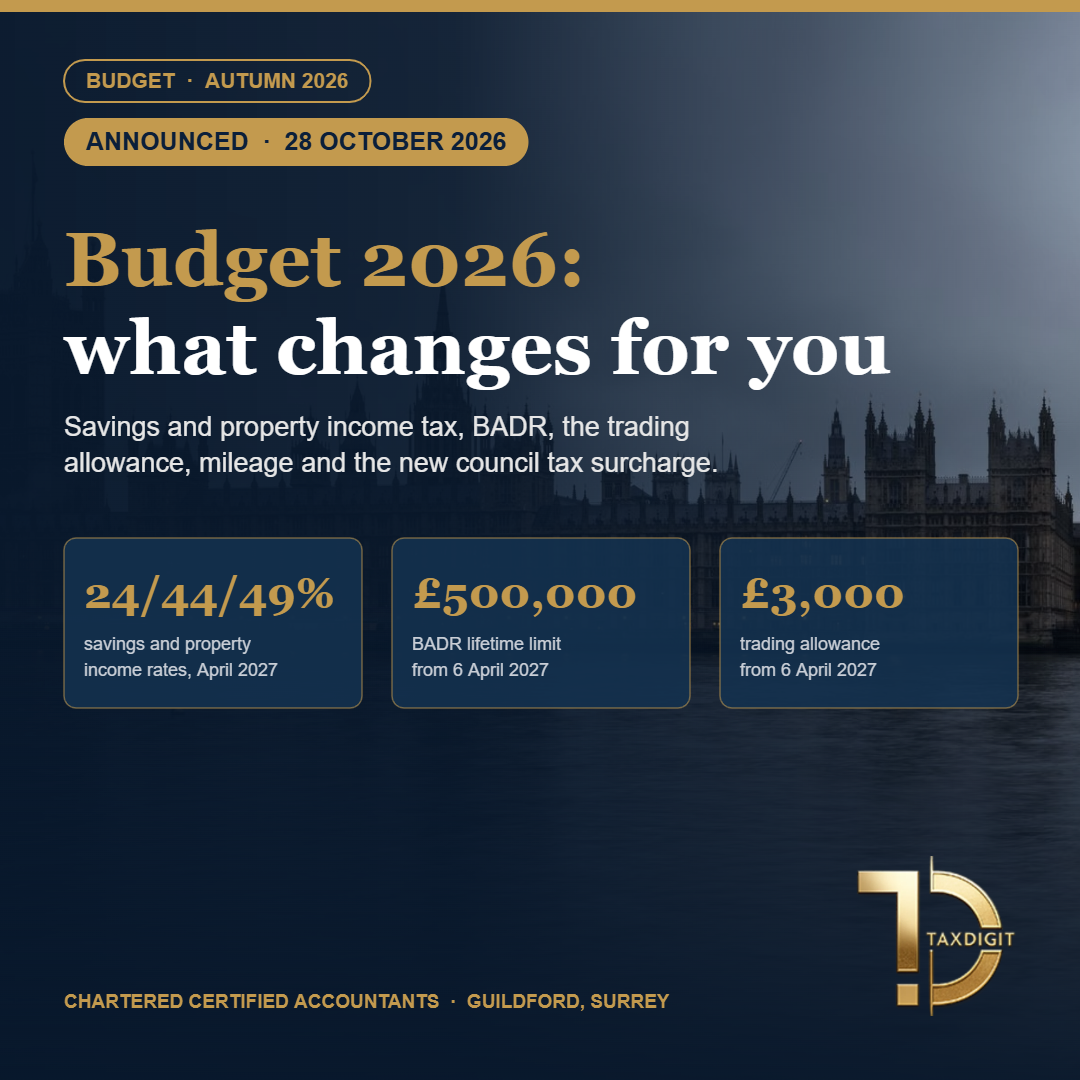
In short: the Autumn Budget on 28 October 2026 left the headline income tax, National Insurance, VAT and corporation tax rates alone, but it changed several things that matter to owner-managed companies, landlords, sole traders and anyone moving to or leaving the UK. From 6 April 2027 the tax rates on savings and property income rise by four points to 24%, 44% and 49%; the Business Asset Disposal Relief lifetime limit halves to £500,000; the trading allowance triples to £3,000; the approved mileage rate above 10,000 miles rises to 35p; and a new High Value Council Tax Surcharge of £2,500 to £7,500 a year starts in April 2028 for homes worth £2 million or more. Every figure below was read on GOV.UK on 2 November 2026 and the source is named next to it.
The Budget 2026 changes at a glance
The table lists each measure, the figure, the date it takes effect and the GOV.UK document it comes from. The Finance Bill can still amend the detail before it becomes law.
| Measure | What changes | From | Source |
|---|---|---|---|
| Savings income tax rates | Basic, higher and additional rates rise to 24%, 44% and 49% (from 20%, 40% and 45%) | 6 April 2027 | OOTLAR, Income Tax: Savings Income Tax Rates for tax year 2027-2028 |
| Property income tax rates | Basic, higher and additional rates of 24%, 44% and 49% on rental profits in England, Wales and Northern Ireland | 6 April 2027 | OOTLAR, Income Tax: Property rates for tax year 2027-28 |
| Trading allowance | Rises from £1,000 to £3,000; the Self Assessment reporting threshold for trading income also becomes £3,000 | 6 April 2027 | Increasing the trading allowance (28 October 2026) |
| Business Asset Disposal Relief | Lifetime limit falls from £1,000,000 to £500,000; qualifying gains remain taxed at 18%; relief already claimed counts towards the new limit | Disposals on or after 6 April 2027 | New Business Asset Disposal Relief lifetime limit (29 October 2026) |
| New relief for founders | A lower Capital Gains Tax rate on qualifying disposals of shares; technical consultation closes 30 November 2026 | Disposals on or after 6 April 2027 | OOTLAR, Capital Gains Tax: Introduction of a new relief for founders |
| Approved mileage rates | Rate above 10,000 business miles rises from 25p to 35p per mile; the first 10,000 miles stay at 55p | 6 April 2027 | OOTLAR, Approved Mileage Allowance Payments and Self-Employed Simplified Mileage Rates |
| High Value Council Tax Surcharge | Annual charge on homes in England valued at £2 million or more: £2,500 (£2m to £2.5m), £3,500 (£2.5m to £3.5m), £5,000 (£3.5m to £5m), £7,500 (£5m and above); paid by the owner, not the occupier; valuations as at April 2026 | April 2028 (first bills March 2028) | High Value Council Tax Surcharge (updated 28 October 2026) |
| Corporation tax | Main rate stays at 25% and small profits rate at 19% for the financial year beginning 1 April 2028 | 1 April 2028 | OOTLAR, Financial Year 2028 Charge and Rate of Corporation Tax |
| Capital allowances | Main-rate first-year allowance rises to 50% for expenditure from 1 January 2027; main-rate writing-down allowance falls to 12% from 1 April 2027 | 1 January 2027 and 1 April 2027 | OOTLAR, Capital Allowances |
| R&D tax relief | Claim Notification Form no longer required for claims made on or after 1 April 2027; Additional Information Form simplified from autumn 2027 | 1 April 2027 | OOTLAR, R&D Tax Reliefs: Improving the Customer Experience |
| VAT on domestic electricity | Temporary 0% rate extended to 30 June 2027 (it would otherwise have returned to 5% on 1 April 2027) | Until 30 June 2027 | OOTLAR, Extending the Temporary 0% VAT rate for Domestic Electricity |
| Making Tax Digital for Income Tax | No late-submission penalty points for 2027-28 quarterly updates for those joining in April 2027; exemptions for qualifying carers, non-UK resident entertainers and sportspeople and expected non-resident customers continue until further notice | April 2027 | OOTLAR 2.36 and 2.37 |
| Self Assessment payments on account | More regular in-year payments for taxpayers who make payments on account; eligible taxpayers can pay through PAYE | April 2029 | OOTLAR 2.31, More Timely Payments for Self Assessment |
| Company distributions | Distributions framework (capital reductions, buybacks, demergers) modernised; draft legislation in 2027 | April 2028 | OOTLAR 2.15, Modernising the Distributions Framework |
| Securities Transfer Tax | Replaces Stamp Duty and Stamp Duty Reserve Tax on shares | Late 2027, by commencement order | OOTLAR 1.64, Modernisation of the Stamp Taxes on Shares Framework |
| Lifetime ISA | Withdrawal charge for a home above the £450,000 cap falls from 25% to 20%; a First Time Buyer ISA with a 25% bonus on up to £20,000 replaces the Lifetime ISA for new savers from April 2029; the cash ISA limit stays at £20,000 | 29 October 2026 / April 2029 | OOTLAR 2.3 to 2.5 |
| Banking surcharge | Rises to 6% | 1 January 2027 to 31 March 2028 | OOTLAR 1.37 |
| Investors in US LLCs | New double taxation relief for UK resident individuals who hold US LLC interests; claims from early 2028 | Early 2028 | OOTLAR 2.46, Investors in US LLCs and Reverse Hybrids |
What the Budget means for owner-managed companies
Three measures touch almost every small company we act for. The first is the halving of the Business Asset Disposal Relief lifetime limit to £500,000 for disposals on or after 6 April 2027. If you are planning to sell your company or to close it through a members’ voluntary liquidation and take the proceeds as capital, the timing of the disposal now matters: a sale that completes before 6 April 2027 is tested against the £1,000,000 limit, and a sale on or after that date against £500,000, with any relief you have already used counted against it. GOV.UK also sets out an anti-forestalling rule for contracts signed before 6 April 2027 but completed after it, so a contract signed to beat the deadline needs a commercial reason that can be evidenced. The second measure is the rise in the first-year allowance to 50% for main-rate plant and machinery bought from 1 January 2027, which brings forward relief for companies investing in equipment, while the writing-down allowance on the remaining pool falls to 12% from 1 April 2027. The third is the removal of the R&D claim notification form for claims on or after 1 April 2027, which takes away a trap that has cost late-notifying companies their whole claim.
The corporation tax rates themselves do not move: 25% main rate and 19% small profits rate are confirmed for the year beginning 1 April 2028. The planned reform of the distributions framework from April 2028 will change how capital reductions, share buybacks and demergers are taxed; draft legislation is promised in 2027 and we will cover it when it is published.
Landlords and savers: four points more tax from April 2027
The largest single change for individuals is the four-point rise in the rates on savings and property income. From 6 April 2027 a basic-rate taxpayer pays 24% on rental profits and interest, a higher-rate taxpayer 44% and an additional-rate taxpayer 49%, against 20%, 40% and 45% in 2026-27. Dividend rates are not changed by this Budget. Non-resident landlords under the Non-Resident Landlord Scheme are taxed at the property income rates on their UK rental profits, so the rise applies to them too. For a landlord with £20,000 of taxable rental profit in the higher-rate band, the extra tax from April 2027 is £800 a year; the personal allowance and the £50,270 higher-rate threshold remain frozen.
Owners of homes in England worth £2 million or more should also diary April 2028, when the High Value Council Tax Surcharge starts. The charge is banded, from £2,500 a year for a home valued between £2 million and £2.5 million to £7,500 a year for a home worth £5 million or more, and it falls on the owner rather than the occupier. Values are assessed as at April 2026. GOV.UK does not yet say how properties owned through companies or by non-residents are treated, so we will update this guide when the legislation is published.
Sole traders and side incomes
The trading allowance rises from £1,000 to £3,000 on 6 April 2027, and the threshold at which trading income must be reported through Self Assessment rises to the same figure. In practice someone with a small side income of up to £3,000 a year from 2027-28 will neither pay tax on it nor have to file a return for it, unless they have another reason to file. The approved mileage rate above 10,000 business miles rises from 25p to 35p per mile from the same date, with the first 10,000 miles staying at 55p; the same figures apply to the simplified mileage rates used by the self-employed. Taxpayers joining Making Tax Digital for Income Tax in April 2027 (income over £30,000) will not receive late-submission penalty points for the 2027-28 quarterly updates, and from April 2029 payments on account move to more regular in-year payments.
Moving to the UK or leaving it
There was no change to the UK tax residence rules, the four-year foreign income and gains regime or the temporary repatriation facility in this Budget. Two measures are still worth noting. For anyone selling a UK company or business before emigrating, the Business Asset Disposal Relief change above makes the date of disposal relative to 6 April 2027 a planning point in its own right; our guide to closing or selling a UK company when you leave the UK covers the full sequence. For UK residents who hold interests in US limited liability companies, a new double taxation relief will let them claim credit for US tax paid on the LLC’s earnings against UK tax on the distributions, with claims possible from early 2028. If you are arriving in the UK with overseas income, our page on moving to the UK: immigration and tax explains the first-year position, and our UK accountant for non-residents page covers the continuing obligations of someone who keeps UK income after leaving.
What did not change
- Income tax rates on earnings and the main National Insurance rates: unchanged; the personal allowance and thresholds remain frozen.
- Dividend tax rates: no new change in this Budget.
- VAT rate and VAT registration threshold: unchanged.
- Corporation tax: 25% and 19% confirmed for the year from 1 April 2028.
- Main Capital Gains Tax rates: unchanged.
Frequently asked questions
When do the new savings and property income tax rates start?
On 6 April 2027, for the 2027-28 tax year. The rates are 24%, 44% and 49%. Source: GOV.UK, Budget 2026 Overview of tax legislation and rates, published 28 October 2026.
Has Business Asset Disposal Relief been abolished?
No. The relief continues at an 18% rate, but the lifetime limit falls from £1,000,000 to £500,000 for qualifying disposals made on or after 6 April 2027. Relief claimed in the past counts towards the new limit. Source: GOV.UK policy paper of 29 October 2026.
Does the BADR change affect a members’ voluntary liquidation?
Yes, where the distributions are capital and qualify for the relief. The date of the distribution determines which limit applies, so a company closure planned for 2027 should be timed with the 6 April 2027 date in mind. Our company closure page explains the strike-off and MVL routes.
What is the new trading allowance?
£3,000 a year from 6 April 2027, up from £1,000. Trading income up to £3,000 does not need to be reported through Self Assessment from 2027-28, unless you have another reason to file. Source: GOV.UK, Increasing the trading allowance, 28 October 2026.
What are the approved mileage rates from April 2027?
55p per mile for the first 10,000 business miles and 35p per mile above that, from 6 April 2027. The 25p rate for miles above 10,000 applies until then. Source: GOV.UK OOTLAR, 28 October 2026.
What is the mansion tax and when does it start?
Its formal name is the High Value Council Tax Surcharge. It applies to residential properties in England valued at £2 million or more as at April 2026, from April 2028, with first bills in March 2028. The annual charge is £2,500, £3,500, £5,000 or £7,500 depending on the band, and the owner pays it. Source: GOV.UK, High Value Council Tax Surcharge, updated 28 October 2026.
Did the corporation tax rate change?
No. The main rate stays at 25% and the small profits rate at 19%, now confirmed for the financial year beginning 1 April 2028.
Did the Budget change the rules for people moving to the UK or leaving it?
No change was announced to the Statutory Residence Test, the four-year foreign income and gains regime or the temporary repatriation facility. The BADR lifetime limit and the new US LLC relief are the two measures most likely to affect internationally mobile clients.
Is VAT on electricity still 0%?
Yes for domestic electricity: the temporary 0% rate is extended to 30 June 2027. Source: GOV.UK OOTLAR 2.20.
When does the Securities Transfer Tax start?
In late 2027, by commencement order, replacing Stamp Duty and Stamp Duty Reserve Tax on shares. Source: GOV.UK OOTLAR 1.64.
Figures read on GOV.UK on 2 November 2026 from the Budget 2026 Overview of tax legislation and rates (published 28 October 2026), the Business Asset Disposal Relief policy paper (29 October 2026), the trading allowance policy paper (28 October 2026) and the High Value Council Tax Surcharge page (updated 28 October 2026). Measures can change before the Finance Bill is enacted. This article is general information, not advice on your own position.